

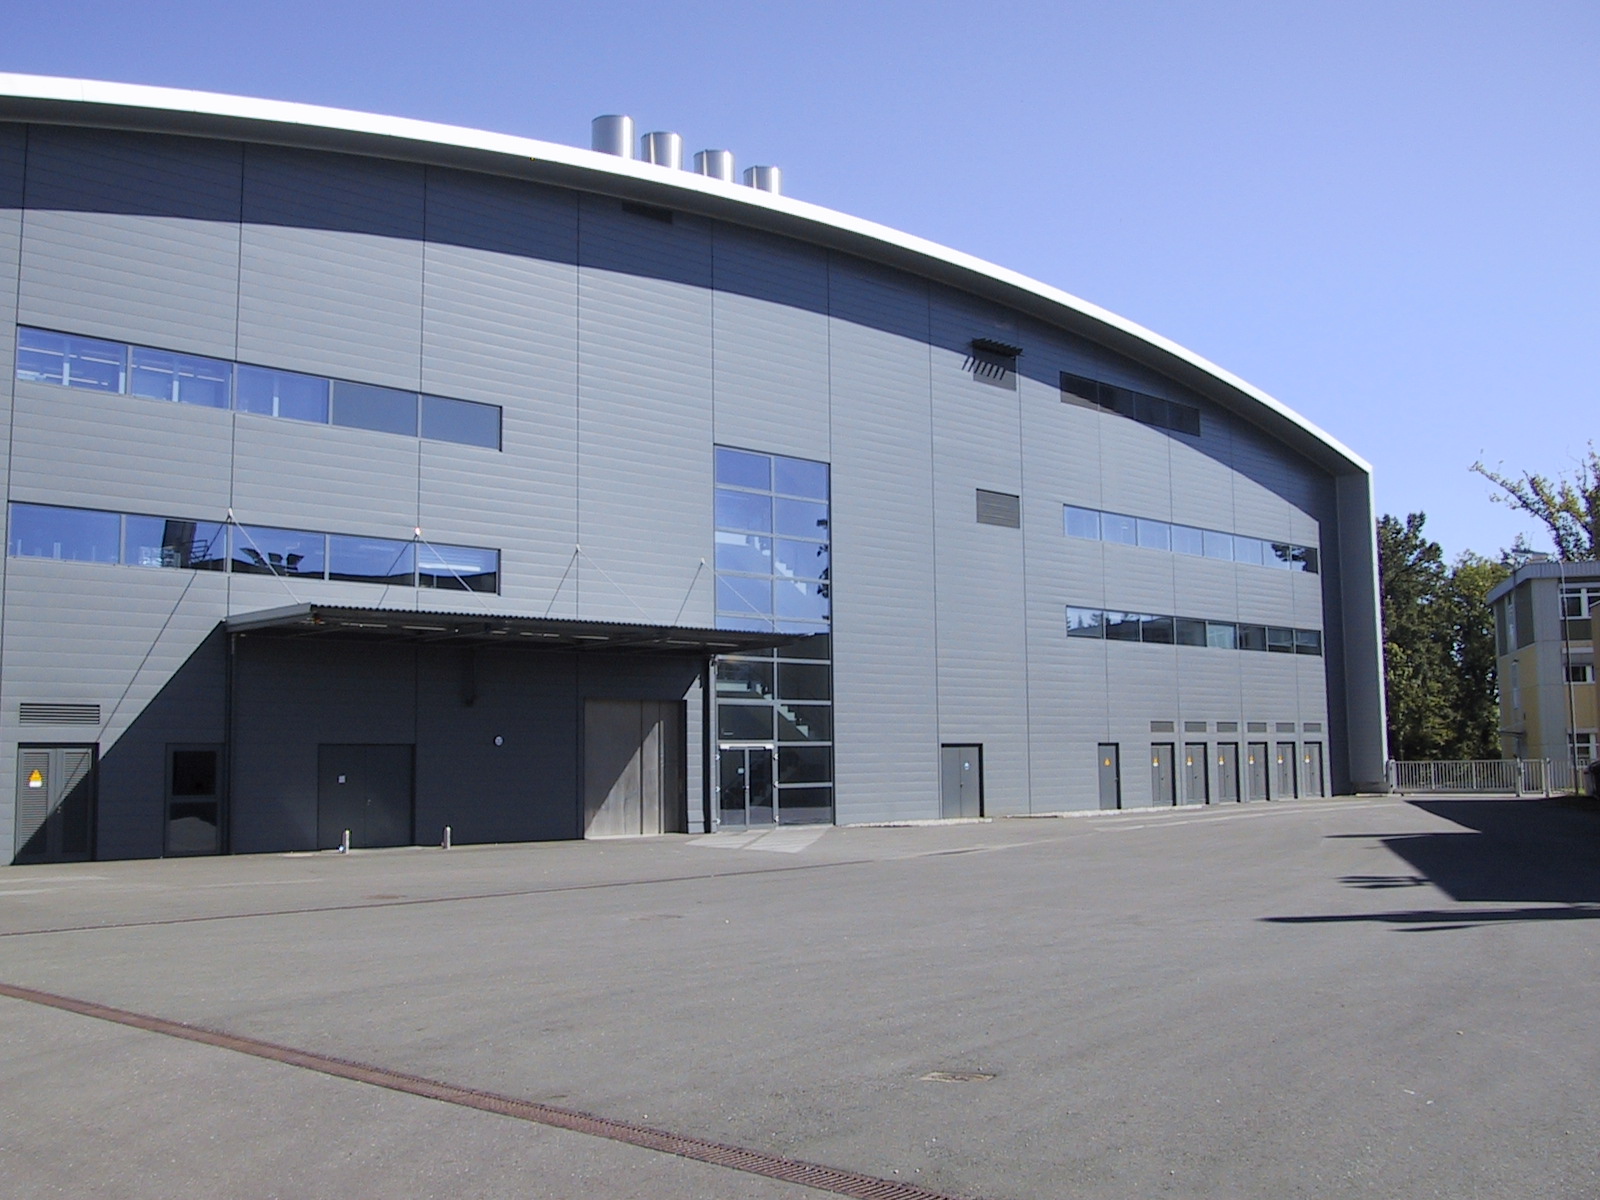
The most important construction sites in the world right now do not look dramatic: windowless boxes on flattened land in Arizona, Saxony, Kumamoto and Gujarat, inside which the air is a thousand times cleaner than an operating theatre. These are the new semiconductor fabs, the front line of a subsidy race among the United States, Europe, Japan, India and China to secure the chips on which economies and militaries now depend.
The first act of the chip race was panic — shortages that idled car plants and taught finance ministers the words ‘leading edge’. The second act is execution, and it is proving harder than the announcements. Fabs run years late and billions over budget; the skilled technicians to staff them are scarce everywhere; and each new plant needs an ecosystem of chemical suppliers, equipment service and ultrapure water that cannot be subsidised into existence overnight. Our technology desk has followed the cranes as faithfully as the press releases.
The Chokepoints Nobody Can Buy Quickly
A fab is not the industry; it is the visible tip of a chain with surreal concentrations. One Dutch company makes every extreme ultraviolet lithography machine on earth. A handful of firms dominate the photoresists, the wafers, the design software. Taiwan still fabricates the overwhelming majority of the most advanced logic chips. Subsidy programmes can move assembly and older-node capacity relatively fast — and are doing so — but the frontier’s centre of gravity shifts slowly, measured in decades of accumulated process knowledge.
That is why policy has turned to ‘friend-shoring’ the whole chain rather than any single link: packaging plants in Vietnam and Malaysia, materials in Japan, equipment in the Netherlands, design in the US and India. Strategists at institutions such as the Center for Strategic and International Studies describe the goal not as self-sufficiency — impossible — but as resilience: no single earthquake, blockade or election able to stop the world’s chip supply.
The Bill and the Bet
The combined public money committed globally runs to hundreds of billions, with private investment multiples higher. Sceptics ask whether the world is building tomorrow’s glut, as it has before in memory chips. The industry’s answer is demand: AI accelerators have added an apparently bottomless new category of chip consumption on top of cars, appliances and everything else getting smarter.
The Talent Is the Real Substrate
Ask fab executives what actually limits them and the answer is rarely money or machines. It is people: process engineers with twenty years of yield intuition, technicians who can keep a fab’s thousands of tools in tune. Taiwan and Korea accumulated that workforce over generations; the new fab nations are trying to import, train and borrow it simultaneously — flying in experienced engineers, founding semiconductor curricula, and discovering that a leading-edge fab is a university that happens to make chips.
India’s bet leans into its design workforce — a large share of the world’s chip designers are Indian — extending into manufacturing from strength. Japan is reviving a storied industry with foreign partners. Each nation’s strategy differs; the shared insight is that sovereignty in semiconductors is ultimately a workforce with a flag. The factories are the easy part to photograph.
The second act has a slower tempo than the first: fabs take years, workforces take longer, and the politics of subsidies must survive election cycles in four capitals at once. What the race has already changed, permanently, is the assumption underneath the industry — that efficiency alone should decide where the world’s most strategic product gets made.
Either way, the map is being redrawn in concrete. A decade from now, ‘where chips come from’ will have a longer, more complicated answer — which, for the governments writing the cheques, is precisely the point. More at techwaterfall.com.in.
